MarketEx
"High-performance trading exchange and real-time market order book simulation."
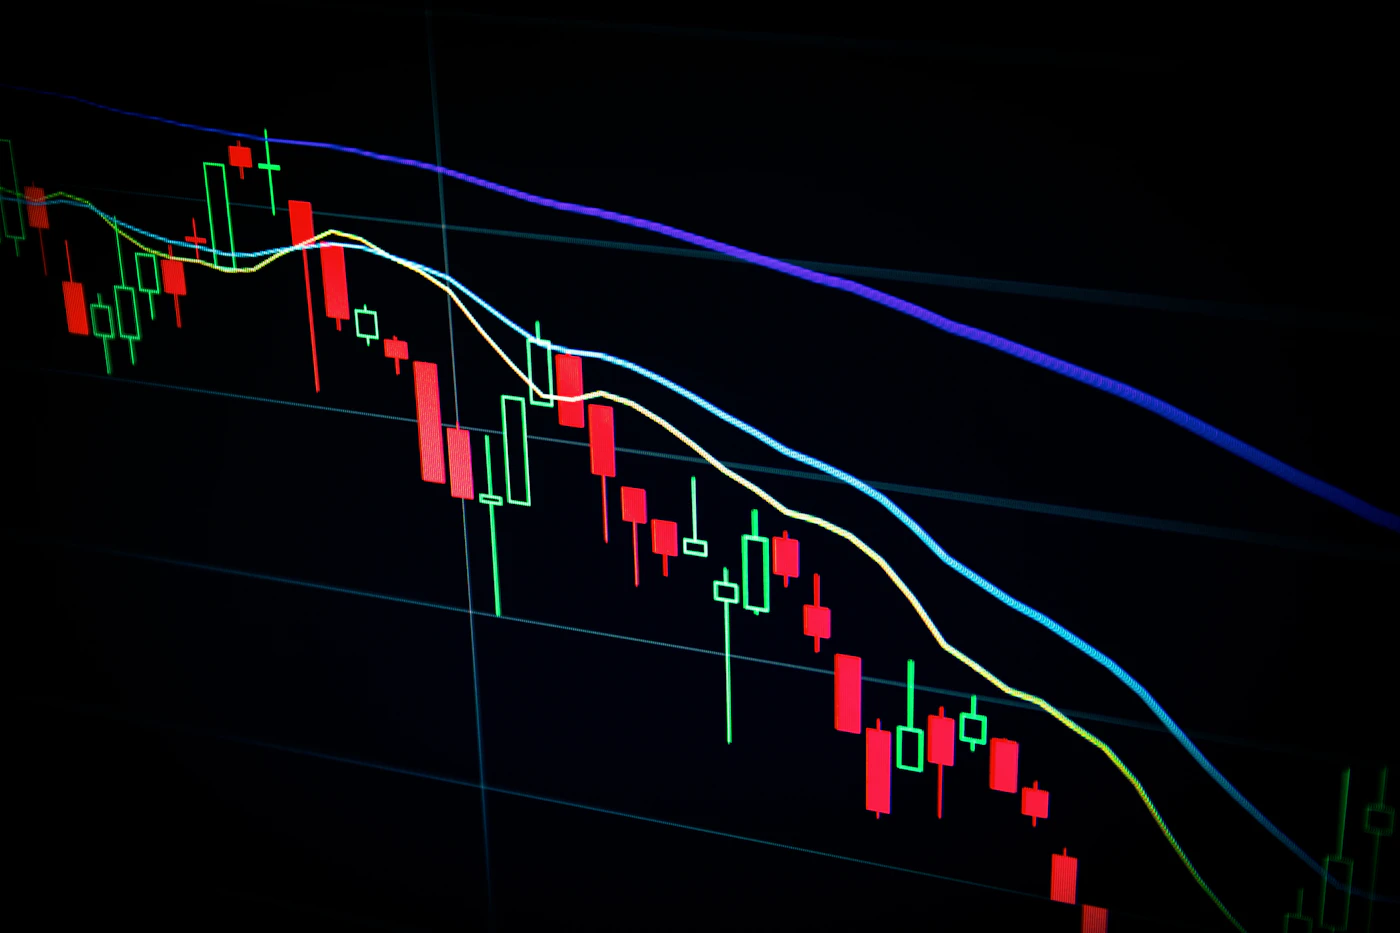
MarketEx is a simulated financial trading exchange built to model limit order books, bid-ask matching algorithms, and low-latency price dissemination. It supports simulated equity and cryptocurrency pairs with streaming candlestick charts and real-time portfolio tracking.
Executive Summary
Trading platform & exchange simulationThe Challenge
Standard financial educational simulators often suffer from delayed polling, unrealistic order execution, and unresponsive interfaces during high trading volume events.
Key Objectives
Limit Order Book Engine
Deterministic price-time matching supporting Market, Limit, and Stop-Loss order executions.
Real-Time WebSocket Feed
Sub-millisecond market depth updates and trade execution notifications pushed directly to browsers.
Interactive Candlestick Charts
Dynamic charting with multiple timeframes (1m, 5m, 1h, 1D) and volume indicators.
Portfolio & PnL Analytics
Real-time margin calculation, unrealized and realized PnL tracking, and transaction ledgers.
Frontend
- React
- TypeScript
- Tailwind CSS
- Canvas Charts
Backend
- Node.js
- TypeScript
- WebSocket (ws)
Database & Cache
- Redis (Pub/Sub & Caching)
- PostgreSQL
Tools & Utilities
- Docker
- Git
- Postman
System Architecture & Data Flow
Engineered around an event-driven architecture. Incoming order requests are validated by an API gateway, passed to a single-threaded in-memory order book matching engine to avoid lock contention, and committed to Redis. Redis Pub/Sub fans out execution reports to WebSocket worker nodes, which push low-latency market depth deltas to active browser sessions.
Development Approach
Modeled the order book using doubly linked lists index-mapped by binary search trees for O(1) order cancellation and O(1) best bid/ask lookups. Profiled WebSocket message serialization to minimize memory allocations under rapid bursts.
Challenges Encountered & Solutions
Maintaining clock synchronization and preventing race conditions during concurrent order placements. Addressed this by enforcing single-threaded deterministic event queuing for matching transactions combined with optimistic locking on user account balances.


Click any image to view in high-resolution lightbox.
Project Outcomes
Demonstrated sustained processing of over 10,000 simulated orders per second with sub-5ms client-side rendering latency.
Future Roadmap
- →Backtesting engine for algorithmic trading strategies written in Python.
- →Decentralized wallet connectivity (Web3 / MetaMask).
- →Fix/QuickFIX protocol integration for institutional connectivity.